UK to increase the additional banking surcharge from 3% to 6%
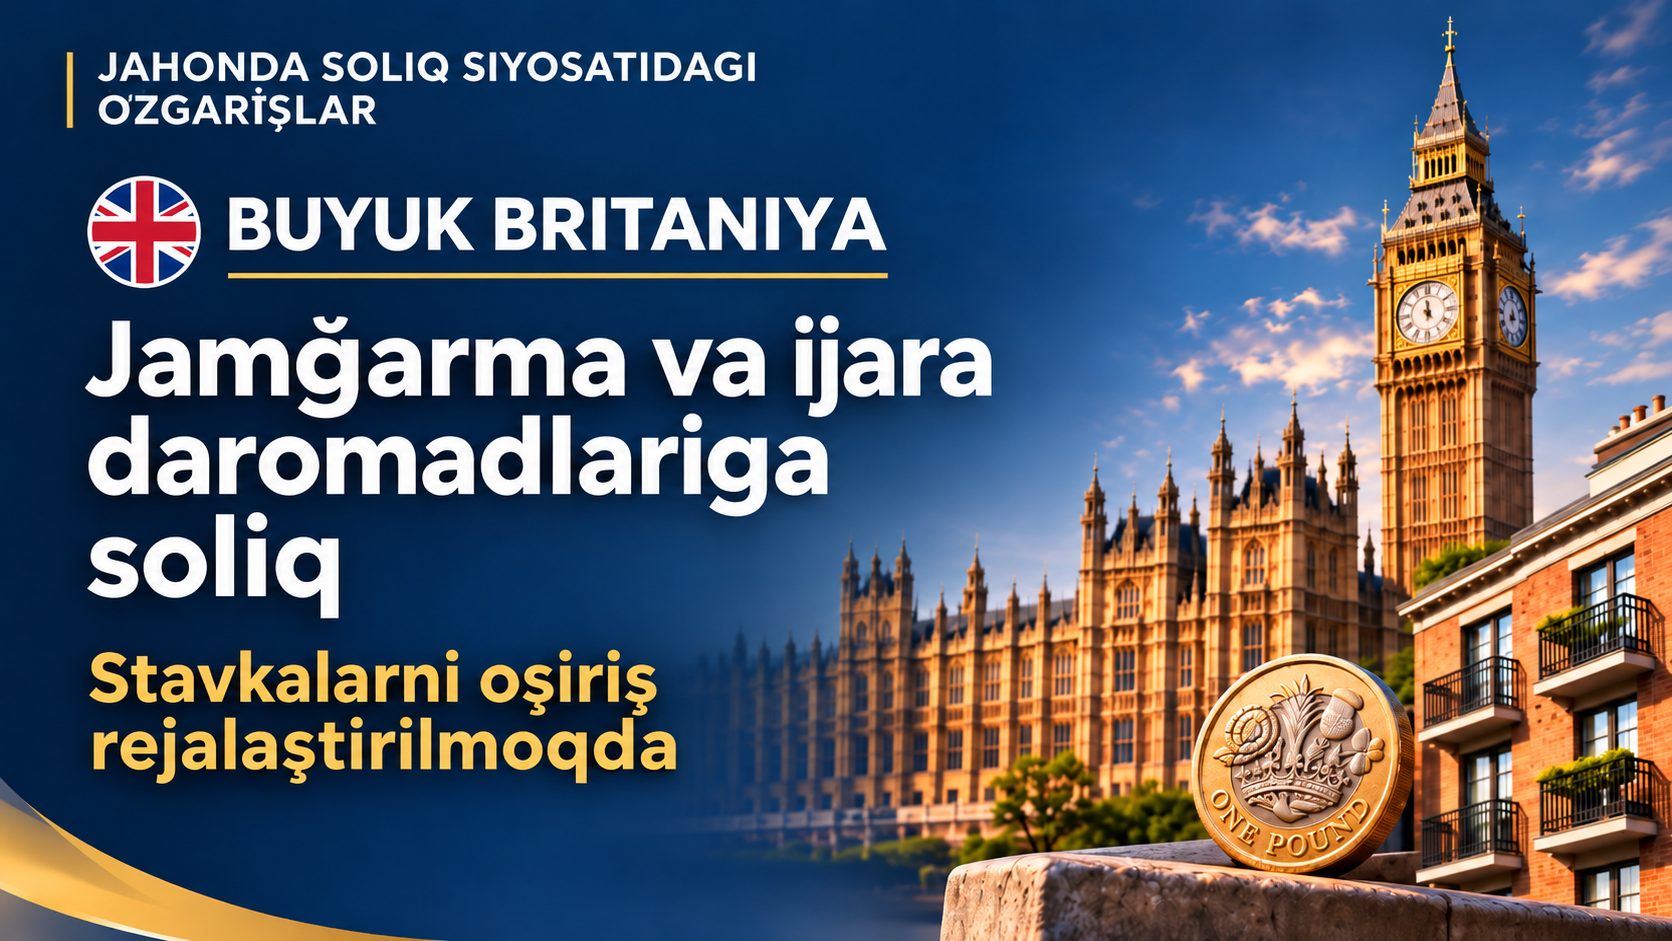
As part of the United Kingdom's 2026 Budget, a temporary doubling of the Bank Corporation Tax Surcharge has been proposed:
🔹 current rate — 3%;
🔹 new rate — 6%;
🔹 effective period — 1 January 2027 to 31 March 2028, covering 15 months.
In the United Kingdom, the main Corporation Tax rate for large companies, including banks, is 25%. In addition to this tax, banks are subject to a special surcharge.
Following the increase in the surcharge from 3% to 6% on 1 January 2027, the combined tax rate applicable to the relevant portion of banks' profits exceeding the specified threshold will be: 25% Corporation Tax + 6% banking surcharge = 31%.
However, the 31% rate does not apply to a bank's entire profit, but only to the relevant portion of profits exceeding the £100 million allowance.
Through this temporary measure, the government plans to raise approximately £1.5 billion in additional revenue.
💡 How will the additional revenue be used?
The additional revenue will be directed towards financing support measures for households and businesses amid rising energy costs. These include measures to reduce household electricity expenses and provide financial assistance to certain families with their energy bills.
🇺🇿 What tax rules apply in Uzbekistan?
Under Article 337 of the Tax Code of the Republic of Uzbekistan:
🏦 the profit tax rate applicable to banks is 20%;
📊 this rate applies to banks' taxable profits;
➕ no separate additional surcharge equivalent to the UK's Bank Corporation Tax Surcharge is provided for banks.
Therefore, a direct comparison of the tax rates in the two countries would be misleading:
🇬🇧 In the United Kingdom, the combined tax rate applicable to the relevant portion of banks' profits exceeding the specified threshold is 31% — comprising 25% Corporation Tax and a 6% additional banking surcharge;
🇺🇿 In Uzbekistan, 20% is the main profit tax rate applicable to banks.
🔗 UK Government — GOV.UK | Tax Code of Uzbekistan